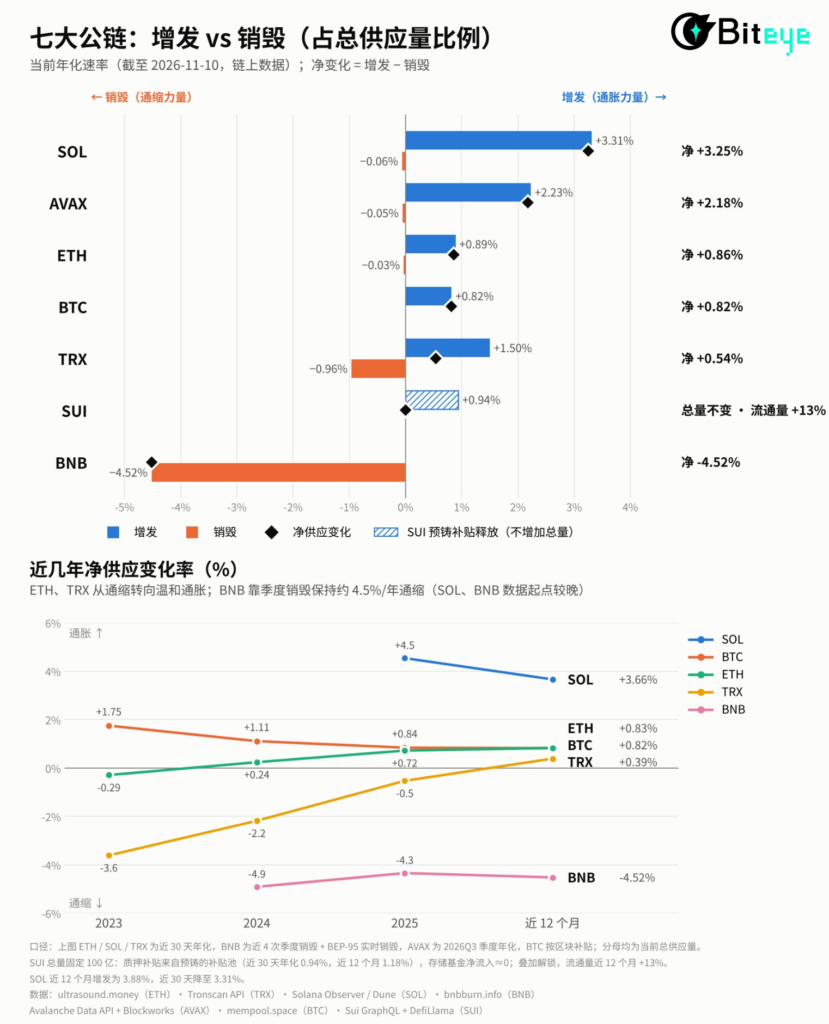
Historical report: This article is based on Biteye’s analysis published by PANews on November 11, 2026. The figures below reflect the periods specified in that report, not current network conditions.
In a November 8 post on X, Vitalik Buterin revisited a familiar argument about ETH: more Ethereum activity generates more fees, which means more ETH is burned. According to Biteye’s account of the post, Buterin cautioned that fee burning is not a reliable floor for ETH’s valuation. Fees generated by speculation can shrink when markets cool.
Buterin still supported EIP-1559, the mechanism that burns Ethereum’s base fee. Biteye reported that he would not consider it a problem if future burns remained below 10% of new issuance. Pursuing higher fees simply to increase burns, he argued, could harm Ethereum’s decentralization and long-term development.
What the supply figures show
Biteye reported that ETH supply had grown about 1.37% in total since the 2022 Merge. Over the 30 days preceding its analysis, burns offset only about 3.2% of new issuance. That weakens the simple “more usage, more burns, less supply” narrative, but it does not by itself establish what ETH is worth.
The comparison across chains also shows why burn totals cannot be read in isolation:
- BTC has an approximately 21 million-coin cap. At a 3.125 BTC block reward and an assumed average of one block every ten minutes, Biteye estimated about 164,300 new BTC annually, or roughly 0.82% supply inflation.
- SOL has ongoing issuance designed to decline over time. After SIMD-0096, priority fees go to validators and only 50% of base fees are burned; Biteye said daily burns at one point fell to around 700 SOL.
- BNB has no ongoing issuance and reduces supply through quarterly Auto-Burn and BEP-95 fee burns, targeting a total supply of 100 million BNB.
- TRX burns fees paid for network resources, but users can also obtain those resources by staking or renting them. More USDT transfers therefore do not necessarily mean proportionally more TRX burned.
- AVAX has a 720 million-coin cap and burns fees on its X, C and P chains, while issuing rewards to validators. Biteye reported that cumulative burns of about 5.18 million AVAX as of early November 2026 had not offset issuance.
- SUI has a fixed total supply of 10 billion. Its circulating supply can rise through unlocks; storage fees held in its Storage Fund are not the same as permanently burned tokens.
Why a burn-based valuation falls short
Biteye described a model Buterin discussed: divide the annual value of burned tokens by a discount rate. At $1 billion in steady annual burns and a 4% rate, it produces a theoretical valuation of $25 billion. The word steady matters.
The report put Ethereum’s 2022 burns at about 1.48 million ETH, worth approximately $3.6 billion. From the start of 2026 through November 8, it put burns at about 19,200 ETH, worth approximately $43 million. Annualizing that latter dollar figure to roughly $50 million would produce a model valuation near $1.25 billion—more than 200 times below the approximately $270 billion ETH market value cited in the report. Biteye presented that gap as a limitation of the model, not evidence that either figure is a definitive fair value.
Buterin instead emphasized Ethereum’s decentralization, censorship resistance, open-source design, privacy and security, according to Biteye. Whether those qualities—and ETH’s use as collateral, a medium of exchange and a native asset in on-chain finance—justify a lasting monetary premium remains a question, not something a burn chart can settle.
Source: panewslab.com (originally published 2026-11-11 11:03 UTC+8)