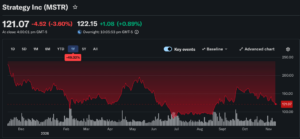
On November 11, 2026, TechFlow reported that MSCI was scheduled to publish its routine index-adjustment final list after the U.S. close that day—5:00 p.m. Eastern time, or 6:00 a.m. Beijing time on November 12. The piece treated removal as a pending decision, not a completed change.
Research firm Solid Intel, as cited by TechFlow, said that if Strategy were dropped from MSCI’s flagship index, passively tracking funds could face selling of up to $2.8 billion. Five digital-asset treasury companies were on a preliminary removal watchlist, including Japan-listed Metaplanet, described as holding about 44,000 bitcoin. TechFlow said Strategy accounted for more than 90% of the circulating market value of the affected group, which is why the review was being read as a test of how index rules hit crypto-treasury stocks.
The rule MSCI actually finalized
TechFlow traced the policy to October 2025, when MSCI opened a consultation on a digital-asset threshold. That draft would have removed companies whose digital assets were 50% or more of total assets from the global investable market index and paused weight increases for related firms.
On October 15, 2026, MSCI finalized a different screen: a non-operating-entity rule based on financial indicators. Under it, a company would be classified as non-operating if it failed an operating-asset test in two consecutive annual reports and missed four of five indicators covering operating assets, expenses, cash flow, and related items.
In a comment letter to MSCI, Strategy said that non-operating classification lacked a basis in generally accepted accounting principles. In its third-quarter report filed with the SEC, the company disclosed the risk that the new parameters could lead to index removal.
What the dollar figures measure
The widely cited amounts are estimates of stock flows, not completed trades.
According to TechFlow’s account of a Crypto Briefing review, JPMorgan analysts calculated that removal from the MSCI flagship index alone would force index funds to sell about $2.8 billion of MSTR shares. If other major index compilers adopted similar rules, estimated cross-index passive selling could reach as much as $8.8 billion.
Those projections are conditional. Passive funds have to match their benchmarks, so they cannot postpone a sale once a stock leaves an index. TechFlow said liquidity pressure would cluster near the effective date rather than follow a manager’s view of the business.
Share sales are not bitcoin sales
Citing Bitcoin Magazine, TechFlow reported that Strategy had recently raised $283.8 million through an at-the-market equity program and bought 1,036 bitcoin, while still holding $4.77 billion in dollar reserves.
As of November 8, 2026, Strategy held 850,364 bitcoin, with a total cost basis of $64.16 billion and an average cost of $75,456.
On the account given, passive selling would happen in the secondary market for the stock. It would not require custodians to sell the underlying spot bitcoin, and the reserve would stay segregated from the index-driven share sale.
What an index seat can change is trading liquidity and the premium of the share price to net assets. TechFlow noted that if that premium narrows, the spread from issuing equity to buy more bitcoin narrows with it, which would slow the equity-funded accumulation loop. That is a funding-channel point, not evidence that the bitcoin position itself would be liquidated.
What the November 11 report left open
The final list was due after the November 11, 2026 close. If a removal were confirmed, TechFlow said the constituent change would take effect after the U.S. close on November 30, 2026, and tracking funds would have to clear the related positions in that window.
At the time of publication, the final list had not been described as out. Whether Strategy or the other names on the preliminary watch would be removed, and whether other index providers would copy the rule, was still ahead of the decision. The $2.8 billion and $8.8 billion figures are research and analyst estimates of possible passive equity selling—not observed flows, and not sales of bitcoin.
Source: techflowpost.com (originally published 2026-11-11 20:06 UTC+8)